Rising Rates, Rising Prices, Stable Inventory
The combination of rising interest rates and prices and stable inventory pushed existing home sales down and prices up, and the Federal Reserve Will Not Help Thaw the Housing Market
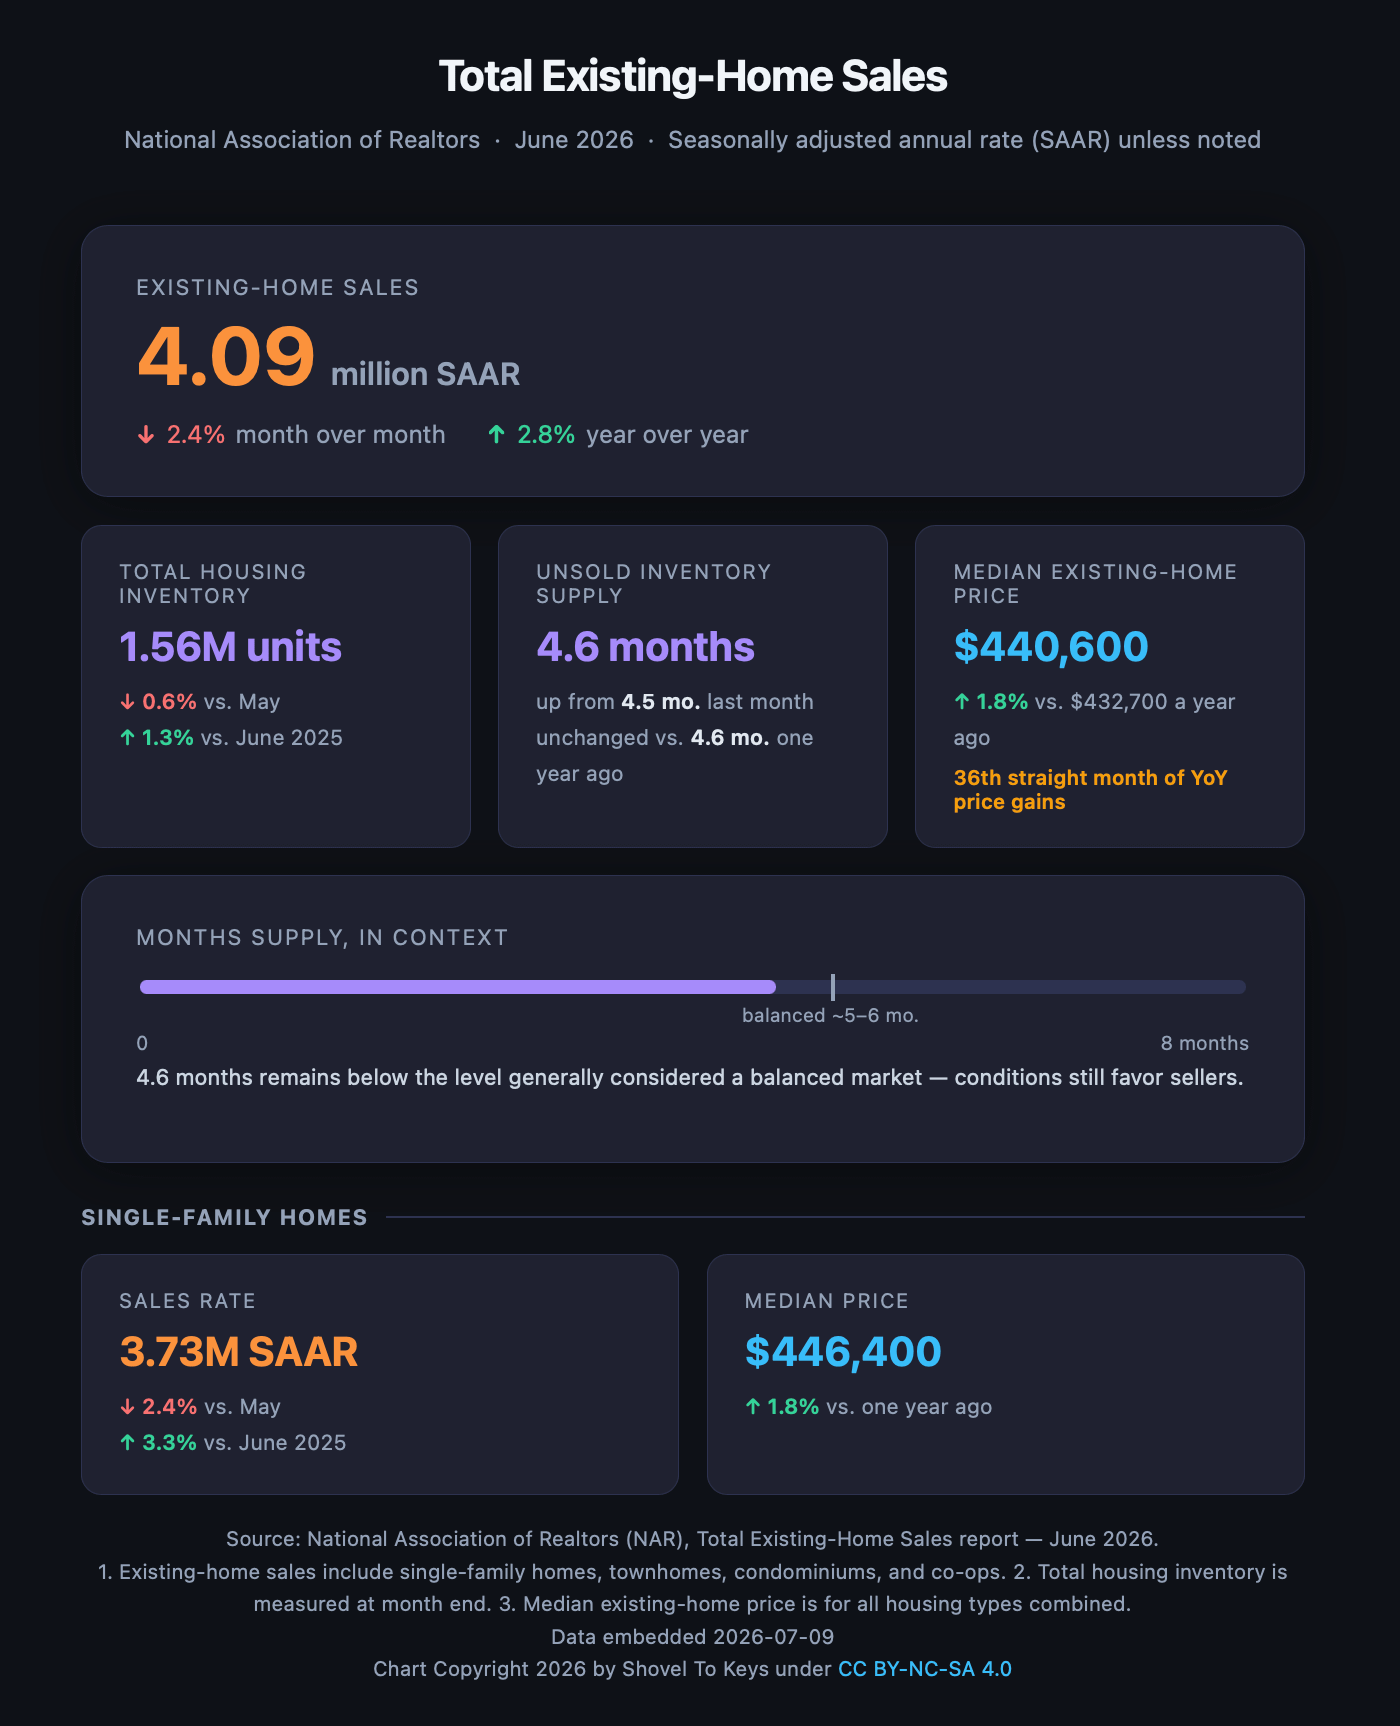
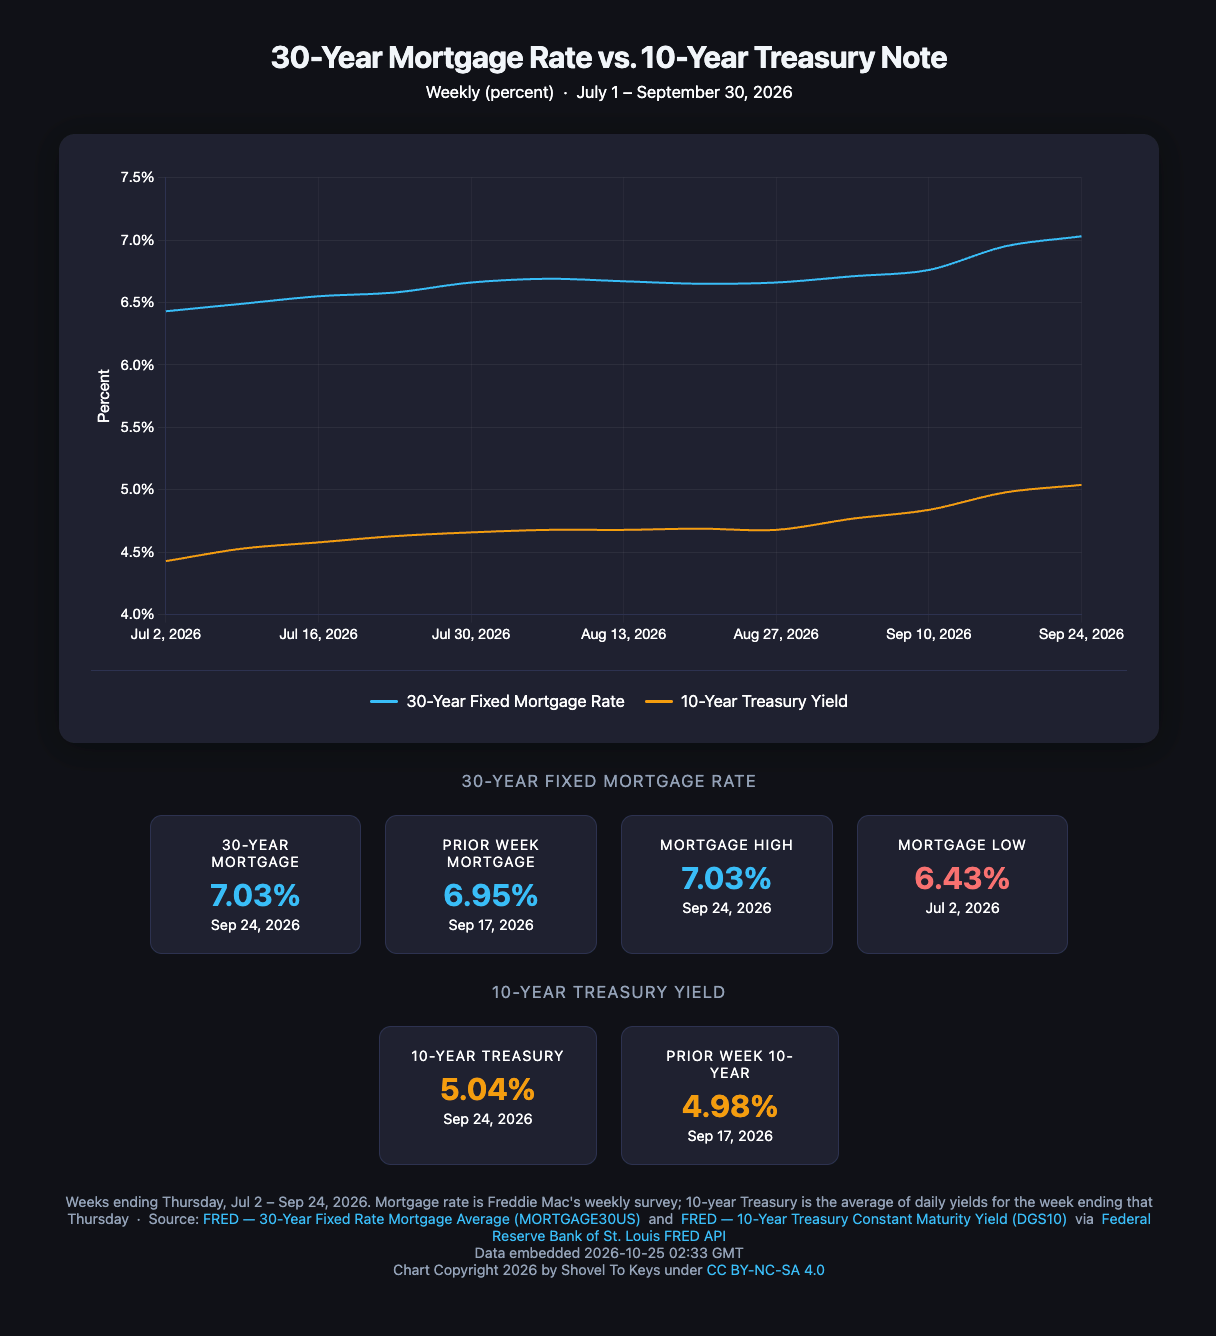
The June 2026 National Association of Realtors existing home report delivered an enormous amount of no real news. With the 30-year mortgage rate averaging 6.49% in June, roughly 0.5% higher than before the Iran War, buyers sensitive to their monthly payment amount faced an affordability challenge that few, if any, housing observers expected when 2026 began. The existing home inventory remained stable, which perpetuated the supply constraint that has sustained home prices. June was lackluster but far from surprising.
The Numbers
The graphic below summarizes the NAR report. The data, except at the bottom of the graphic, include condominium and townhome sales, which are a very small part of the market.
Some observations about the existing home sales market based on the NAR report:
-
Buyers are not clamoring for homes, and sellers are not clamoring for buyers.
-
Sales were up from June 2025 possibly because:
- Despite sharply higher mortgage rates since February, rates still are below the rates from one year ago.
- The reality of a 6+% mortgage rate environment is coalescing with buyers.
- The patience of buyers and sellers is waning, but sellers seem to be a bit more stubborn.
- Buyers see prices still rising despite the “weak” housing market.
-
A 1.8% increase in the median single-family home price seems small.
- At that price point, many recent buyers likely put down no more than 10% and often as little as 3.5% (available with FHA loans).
- The 1.8% increase equals $7,893 of value increase. On a 10% down-payment of $44,640, the return is 17.7%. On a 3.5% down-payment of $15,624, the return is 50.5%. Maybe an investment in Micron did better (NVIDIA did not), but the stability of home ownership might beat the volatility of a semiconductor stock.
For many buyers, being on the housing escalator even at a high price may be better than watching from the bottom as others rise up the escalator. For many sellers, the market price in 2026 represents a substantial profit, even if possibly a bit less than might have been captured at the market peak a few years ago.
Buyer and Seller Sentiment or Federal Reserve Crystal Balls?
In months to come, we can watch for signs that these factors are at play. Or, maybe none of these factors will matter when buyers and sellers across the country begin reading the minutes of Federal Reserve Bank Open Market Committee meetings under the new Chairman, Kevin Warsh. At the most recent meeting, members were evenly divided whether 2026 would see one rate increase or none. Only one member forecast a rate cut. The rate forecast dot-plot read around the world forecasts rates will be largely unchanged for the next two years.
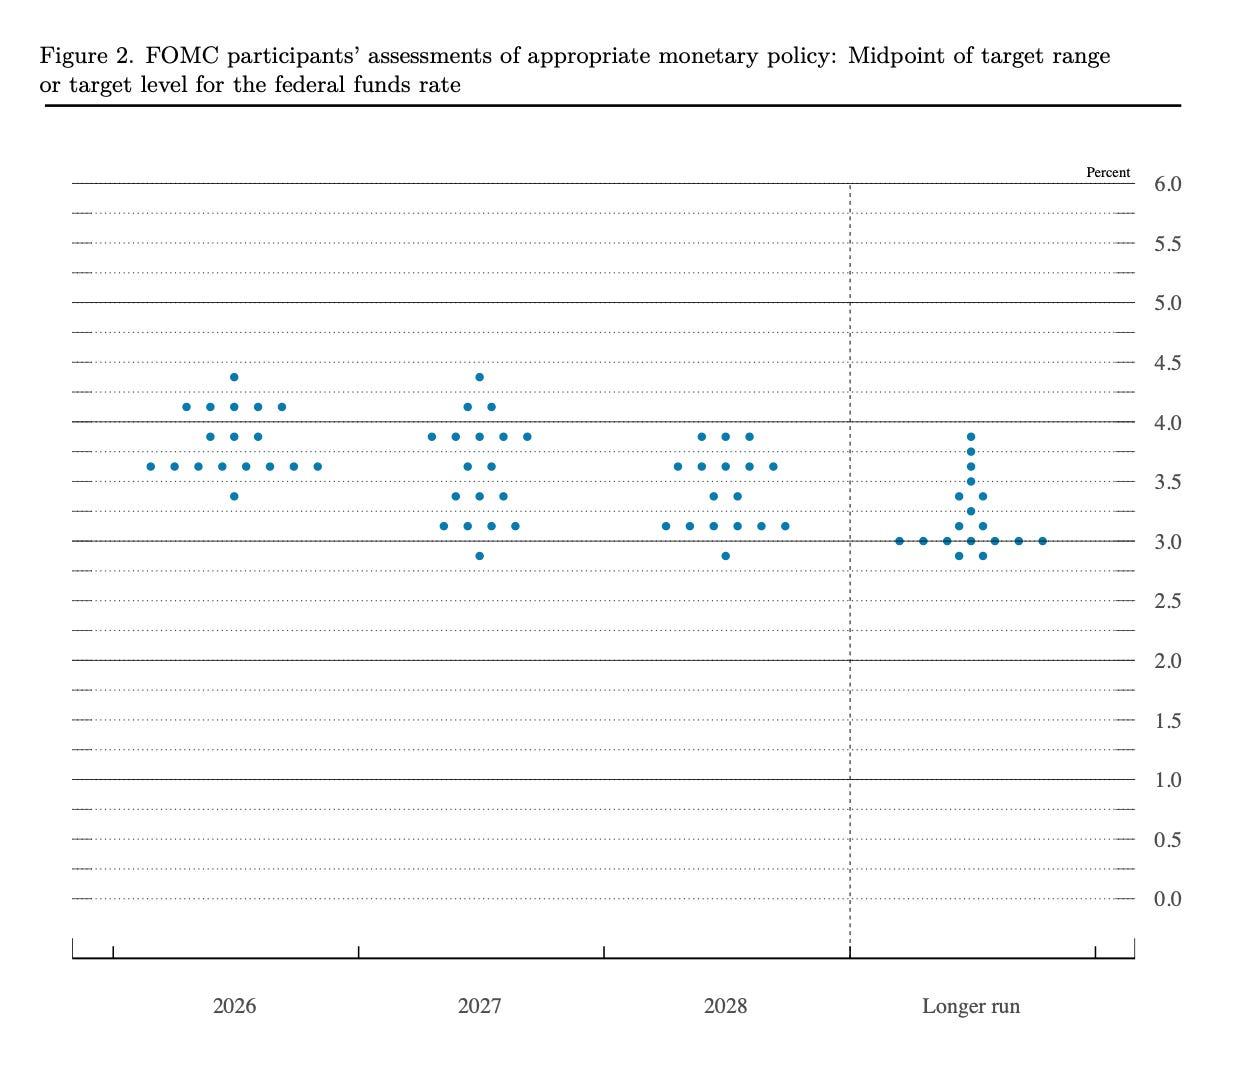
El Niño may bring warmer temperatures, but interest rates will be frozen. If a thawing housing market is your hope, the Federal Reserve will not be bringing the heat.